Tech futures are bouncing Monday morning after the Nasdaq-100 shed 5.5% last week — its worst weekly performance in months. Chip stocks, which closed down nine sessions in a row, are leading the pre-market recovery at +2.6%. Europe is moving the other way: the Stoxx 600 is off 0.8% after a weekend of street protests in Paris that rattled investor confidence ahead of a packed earnings calendar.
Colombia's Largest Vertically Integrated Coffee Producer Is Still a Private Company.
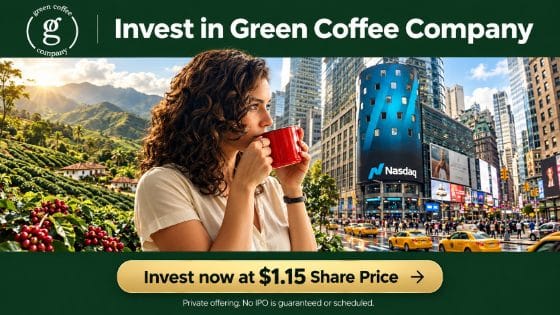
Green Coffee Company grows its own coffee in Colombia, mills it in its own facilities, and sells it in 3,000+ North American stores.
It owns the farms and the mills. Shares are currently $1.15.
Colombia earns 70% of U.S. single-origin coffee sales. Green Coffee Company owns 45 farms there and runs its own mills — grown and processed in-house before it ever reaches a store shelf.
| ✓ | 45 owned farms and 10,000+ acres in Colombia |
| ✓ | Mills processing over 1 million pounds every week, the largest in the country |
| ✓ | Exclusive U.S. and Canada rights to distribute Juan Valdez®-branded coffee |
| ✓ | 3,000+ stores, including Target and Walgreens |
Revenue went from $1 million in 2021 to $26 million in 2025. More than 2,000 investors have already backed the company. Shares are currently available at $1.15, with a minimum of $1,000.50.
Head to Head
| TYPICAL BIG COFFEE BRAND | GREEN COFFEE COMPANY |
| Buys beans from outside growers | 45 owned farms, 10,000+ acres |
| Buys pre-processed beans | Its own wet mills, 1M+ lbs every week |
| Large public or corporate parent | Private company, $1.15 per share |
| No bonus shares | Up to 20% bonus shares |
Reg A+ Round Open Now — $1.15 per share
| $2,500+ 5% |
$5,000+ 7% |
$10,000+ 10% |
| $15,000+ 15% |
$20,000+ 18% |
$25,000+ 20% |
Claim Green Coffee shares at $1.15 →
P.S. In August 2026, GCC became the first private coffee exporter to ship through Colombia's new $800 million Port Antioquia — a route the company projects could cut logistics costs by 20 to 30%.
See the offering at $1.15 per share →
This is a paid advertisement for Green Coffee Company's Regulation A offering. Please read the offering circular at https://invest.greencoffeecompany.com/. Juan Valdez is a licensed brand. The Juan Valdez parties are not sponsors of this offering. No IPO is agreed, guaranteed, or scheduled, and plans may change at any time.
Nasdaq-100 futures are up roughly 1% ahead of Monday's open, snapping a five-day losing streak that trimmed 5.5% from the index. The catalyst for last week's selloff was a pair of reports — one suggesting that major hyperscalers were quietly deferring data center commitments, another showing crude oil crossing $110 a barrel — that together called into question both the revenue side and the cost side of the AI trade simultaneously. Neither issue is resolved this morning, but futures markets are doing what they often do after a week like that: pricing in a pause before re-evaluating.
The standout pre-market mover is the semiconductor ETF, up 2.6% — which would end a streak of nine consecutive down sessions, the worst such run for chipmakers since the 2022 rate cycle began. That streak tells you something: last week's damage was not evenly distributed. Software names held better. It was the hardware and capital-equipment names — the companies tied most directly to how much actual silicon gets built and deployed — that absorbed the most selling. A 2.6% bounce after a 9-session decline is not the all-clear. It is a rest stop.
Only 1,250 complimentary copies of the Quiet Wealth Playbook were printed for this private release.
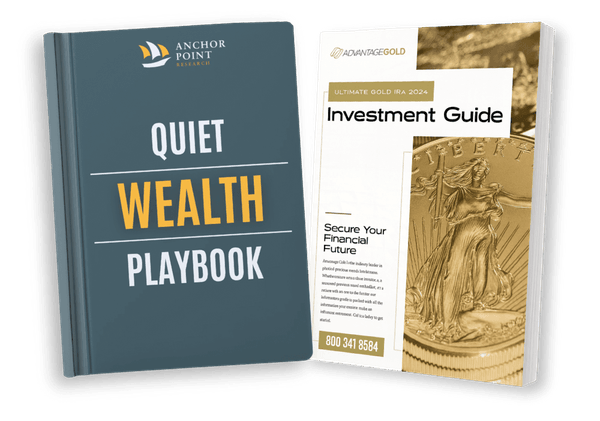
This guide was created for families who want to understand how physical gold can be owned, protected and passed down to the next generation.
Inside:
• Which gold coins and bars you can own outright, with no bank or broker in the middle
• How physical gold can be stored outside the banking system
• Which precious metals may qualify for an IRA
• What families should know before passing gold to heirs
• The beneficiary step that keeps a gold IRA out of probate
There is no charge for a copy. But once all 1,250 copies are claimed, this private release may close.
Europe is not joining the bounce. The Stoxx 600 opened Monday down 0.8%, weighed by political noise that developed over the weekend. France saw its largest street protests in years — demonstrators opposing pension changes and cost-of-living policy, concentrated in Paris and Lyon — which finished Sunday without resolution. French equities are underperforming in early trading. The European situation is a reminder that the macro calendar does not respect market bounce days: French political risk, along with German manufacturing data due mid-week and ECB commentary later in the week, means European investors have a different read on this Monday than their counterparts in New York.
The bigger context for the week ahead is earnings season. This is a dense stretch of the calendar: several mega-cap tech names, major financial companies, and industrial bellwethers are all scheduled to report. Last week's selloff was driven in part by anticipation of what those reports might show — specifically, any guidance language around AI spending commitments from the hyperscalers. The market is, in effect, pricing in the possibility that some of last week's AI capex concerns get confirmed. If they don't — if the big platform companies say they are maintaining or increasing data center budgets — the chip bounce that started pre-market Monday morning will likely have room to continue. If even one major report hedges on capex, the selloff picks back up.
APR Insights
Trump's Executive Order #14330 Moves to the Department of Labor
Here's What Happens Next
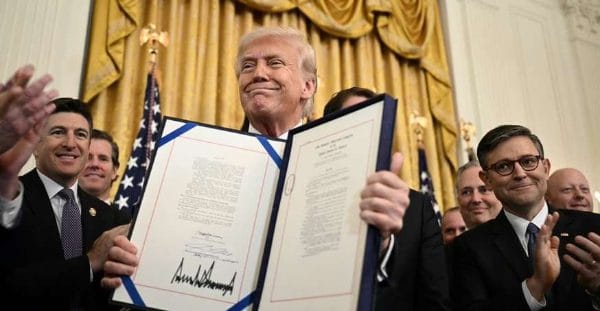
President Trump signed Executive Order #14330 — a sweeping change that could forever alter Americans' retirement accounts.
For the first time ever, physical precious metals like gold are being formally opened to retirement portfolios.
The order is set to take effect in 2027, and J.P. Morgan projects a massive wave of demand could send gold prices toward $8,500 per ounce.
But here's what most people don't realize: You don't have to wait for these changes.
If you're 59½ or older, you can move part of your 401(k) or IRA into gold, today — tax-deferred and penalty-free.
With Executive Order #14330 now signed, the timing has never been clearer:
▶ Gold prices rose 64% in 2025
▶ J.P. Morgan forecasts gold hitting $8,500/oz
▶ Ray Dalio recommends a 10–15% gold allocation for all investment portfolios
If you want to capitalize on this trend, we've created a free guide that explains how to buy physical gold with your retirement account.
Yes, Send Me My FREE Retirement-to-Gold Guide.
© 2026 APR Insights. All rights reserved. Tax benefits depend on individual circumstances. Always consult a tax professional. Not all retirement accounts qualify.
This bounce lands against a backdrop of oil still above $110, a European political situation that has not resolved, and an earnings calendar that has not yet spoken. The pre-market move says traders decided last week's selling went far enough. It does not say the underlying concerns — AI capex doubt, energy inflation, European instability — have been addressed.
The question this week is whether any of the hyperscalers, reporting in the next few days, say something definitive enough to settle the AI capex debate one way or the other. A clear "we are maintaining or increasing infrastructure spending" from one of the major platform companies would likely extend the chip rally through the week. Anything hedged, deferred, or couched in "monitoring macro conditions" language will test whether this Monday morning bounce has legs or is just a relief trade ahead of bad news.
"In freight, we called it the Monday bounce — the load board lights up after a slow Friday, rates tick up, and everybody thinks the market turned. Half the time it held. Half the time by Wednesday you were back where you started. The difference was always whether the actual demand was there or whether carriers were just repricing last week's fear. This Monday in equities reads the same way to me. The load board is up. Whether the freight is real depends on what comes out of earnings calls this week."
Pre-market data: Nasdaq-100 futures +1.0%, S&P 500 futures +0.5%, semiconductor ETF +2.6% (pre-market, October 19, 2026). Stoxx 600 −0.8% in early European trading. Crude oil approximately $110/bbl.
Context: Nasdaq-100 weekly decline: −5.5% (week of October 13–17, 2026). Semiconductor ETF nine-session losing streak prior to Monday. France protests: weekend of October 17–18, 2026, Paris and Lyon. Next Federal Reserve meeting: December 8, 2026. October CPI due first week of November. October jobs report due first Friday of November.