Wall Street's celebration didn't last long. One day after stocks posted their best session since April — led by a near-7% surge in chip stocks — October's inflation report came in hotter than expected. Consumer prices rose 0.4% for the month. Core inflation beat forecasts for the fifth month in a row, rising 0.3%, and the 10-year Treasury yield jumped to 4.94% as futures turned lower. For families already stretched by higher grocery and energy bills, the report is a reminder that the cost-of-living squeeze isn't over yet.
Monday's chip stock rally was real, but Tuesday's CPI print is also real. That is the tension investors are sitting with this morning. The same investors who bought AMD and Nvidia on the dip are now watching the 10-year yield push toward 5% — and a 5% 10-year yield is not a friendly environment for growth stocks priced on future earnings. The bond market is saying the same thing it has been saying all year: the Fed is not done, and the economy is not cooling fast enough to give them cover to stop. Five consecutive months of 0.3% core inflation is not a trend that permits rate cuts. It is a trend that keeps rate hikes on the table.
Only 3,200 complimentary copies were set aside for this release.
And they explain something every American nearing retirement should understand:
How families can prepare their retirement savings for the uncertainty caused by the Iran War, rising living costs, and unpredictable markets.
Because after decades of working, saving, and providing for your family…
The last thing you want is to watch those savings disappear when your family may need them most.
Inside: How physical gold may help diversify retirement savings, and how eligible 401(k) or IRA funds can be used to invest in it.
This guide costs you nothing. But complimentary access is limited to this release.
Click here to get YOUR FREE COPY.
P.S. America has weathered wars and financial crises before. But 3 forces are putting new pressure on family retirement plans:
→ The Iran War: Higher energy costs are hitting household budgets far beyond the battlefield.
→ Inflation: Groceries, healthcare, and everyday expenses keep putting pressure on retirement income.
→ Market uncertainty: One major downturn could force families to rethink years of retirement planning.
You can't control what happens in Washington or overseas.
But you can learn about the options available to protect what you've spent a lifetime building.
Discover how physical gold could fit into a diversified retirement strategy, including important costs and rollover rules.
Yesterday's chip stock rally was not random. It followed four consecutive sessions of heavy selling, and it came on the back of specific news: SpaceX gaining over 8%, AMD up more than 11%, Nvidia firming as buyers stepped back into the sector that had led the selloff. That move was about dip-buyers running a long-term thesis — that AI infrastructure spending continues regardless of political headwinds, that the companies involved have durable earnings power, and that the dip was an opportunity. Today's CPI print tests that thesis immediately. If rates stay higher for longer because inflation will not cooperate, the discount rate that investors use to value future earnings goes up — and that pushes the present value of those earnings down. A chip stock rally and a hot inflation print in consecutive sessions is the market running two contradictory trades at once. One of them is going to be wrong.
A market pattern that has never failed since 1950 is about to collide with Elon's biggest breakthrough. Last time, $10,000 became $350,000 in 12 months.
Marc Chaikin has spent 60 years on Wall Street.
He's worked with Paul Tudor Jones, George Soros and Steve Cohen.
Survived nine bear markets… rang the opening bell at the Nasdaq.
And he says there's one pattern he's relied on his entire career.
A flawless, unbroken market prophecy that has never failed since 1950.
Not once.
All you see is green.
Had you followed it, you'd have made money every single time… with no exception.
And here's the part that matters for your retirement…
Most people don't realize this isn't a prediction...
But a market cycle that IS happening this year.
By the end of this month, it collides with Elon Musk's newest AI breakthrough.
Jeff Brown (the man who picked Nvidia before 36,000%) calls the collision a rare retirement window.
At the stock market's normal pace, it takes 25 years to turn $10,000 into a six-figure nest egg.
When this window opens… it's happened in months.
The last time was 1998, when another revolutionary technology went mainstream.
$10,000 became $185,000 in Magic Software.
$280,000 in Steel Connect.
$366,000 in Qualcomm, in 14 months.
Decades of gains compressed into months.
Marc and Jeff are revealing the pattern, the breakthrough, and the little-known Elon supplier they're both bullish on… free of charge.
>>> Discover the pattern that never failed
— Chris
P.S. This convergence is not normal.
Once it shuts, we'll likely never see it again in our lifetimes.
What the CPI print does to the AI trade is not simple. The direct mechanism is the yield curve: higher yields compress growth stock multiples. But the indirect mechanism matters more in this environment. The investors who bought the AI dip last week were making a thesis bet — that AI infrastructure spending is essentially inelastic to interest rates because the hyperscalers are spending from cash, not credit. Amazon, Microsoft, Alphabet, and Meta are not borrowing to build data centers. They are allocating capital from operating cash flow. If that thesis is correct, then the yield curve is a headwind for retail multiples, not for the underlying business activity that the AI trade is predicated on. The question today is whether institutional investors hold that distinction clearly enough when the 10-year is approaching 5%. History suggests the answer is no. When rates move fast, institutional portfolios deleverage indiscriminately.
Trump's Executive Order #14330 Moves to the Department of Labor
Here's What Happens Next
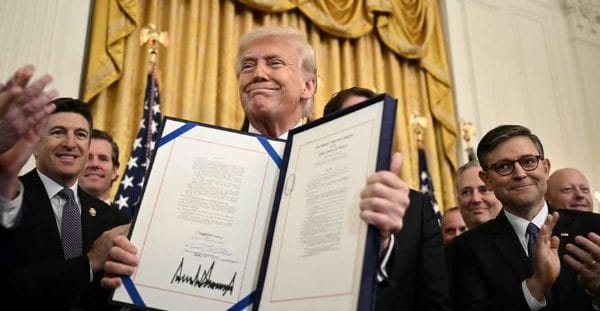
President Trump signed Executive Order #14330 — a sweeping change that could forever alter Americans' retirement accounts.
For the first time ever, physical precious metals like gold are being formally opened to retirement portfolios.
The order is set to take effect in 2027, and J.P. Morgan projects a massive wave of demand could send gold prices toward $8,500 per ounce.
But here's what most people don't realize:
You don't have to wait for these changes.
If you're 59½ or older, you can move part of your 401(k) or IRA into gold, today — tax-deferred and penalty-free.
That means you can beat the rush to gold, while preserving the full tax advantages of your account.
With Executive Order #14330 now signed, the timing has never been clearer:
▶ Gold prices rose 64% in 2025
▶ J.P. Morgan forecasts gold hitting $8,500/oz
▶ Ray Dalio recommends a 10–15% gold allocation for all investment portfolios
If you want to capitalize on this trend, we've created a free guide that explains how to buy physical gold with your retirement account.
Click below now to claim your free guide:
© 2026 APR Insights. All rights reserved. Tax benefits depend on individual circumstances. Always consult a tax professional. Not all retirement accounts qualify.
"Every time the market has a great day, somebody finds a reason to sell it the next morning. Yesterday it was AI stocks going up. Today it's inflation coming in hot. The thing nobody says out loud is that both moves can be right at the same time. AI is a real technology with real earnings. Inflation is a real problem with real consequences. The market can price both simultaneously — it just looks like volatility when it does. The investors who get shaken out by that volatility are the ones who forgot what they owned and why they owned it."
CPI October +0.4% MoM, Core +0.3%: U.S. Bureau of Labor Statistics, November 10, 2026. Consumer Price Index Summary.
10-Year Treasury yield 4.94%: Bloomberg market data, November 10, 2026. Intraday following CPI release.
Monday chip stocks +~7%: Bloomberg market data, November 9, 2026. Best session since April for semiconductor sector.